iPhone Duo At Rs 4.49 Lakh Or SIP: What Could Your Money Become In 10 Years?
The CSR Journal Magazine

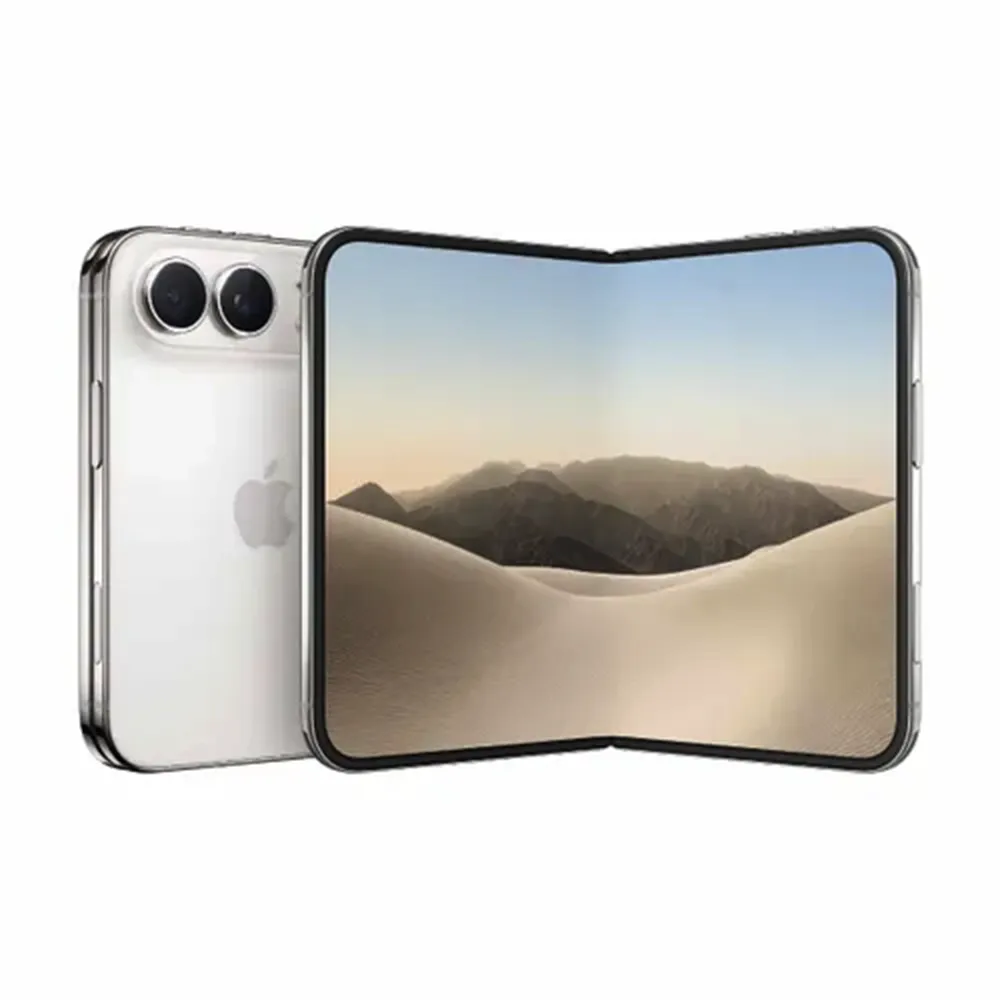
Apple has entered the foldable smartphone market with the iPhone Duo, but its top-end 2TB model comes with a price tag of Rs 4,49,900 in India. At roughly Rs 4.49 lakh, the device costs more than a major financial investment, raising an interesting question for potential buyers: what could the same amount become if it were invested instead?

Apple unveiled the iPhone Duo on September 9, with the 256GB variant starting at Rs 2,99,900 in India. Pre-orders will open on October 16 at 5:30 pm, while sales will begin on October 23. At the other end of the range, the 2TB model costs Rs 4,49,900. If that amount were divided into 12 equal monthly payments, it would work out to around Rs 37,417 a month. Instead of using that money to pay for the phone, an investor could put the same amount into an equity mutual fund through a systematic investment plan, or SIP.

What A One-Year SIP Could Look Like

“An EMI is a SIP running backwards. Same amount. Same schedule. One pays off something that is worth less the day you open the box. The other buys something that has a chance to grow,” said Harsh Soni, founder, Nyvo Money.

To illustrate the difference, suppose Rs 37,417 is invested every month for a year and the SIP earns an assumed annualised return of 12%. The total contribution would be roughly Rs 4.49 lakh. At the end of 12 months, the investment could be worth approximately Rs 4,77,680, resulting in a gain of around Rs 28,680.

The outcome would vary depending on the assumed return. At 8%, the corpus would be around Rs 4.68 lakh after a year. At 10%, it could reach approximately Rs 4.73 lakh, while a 15% return would take it to about Rs 4.85 lakh.

These calculations, however, are only illustrations. Mutual fund returns are market-linked and cannot be guaranteed. A one-year equity investment is particularly difficult to assess using a fixed return assumption because markets can move sharply in either direction.

Why One-Year Equity Returns Can Be Misleading

Soni cautioned against treating 10%, 12% or 15% as predictable one-year equity returns. “For one year, none of them,” he said when asked which return assumption could reasonably be used for a one-year investment.

The five-year annualised return for the flexi-cap fund category during the period considered was 12.92%, which falls within the commonly assumed 10-15% range. But looking at individual 12-month periods produces a very different picture.

Returns fell within the 10-15% range only around 8% of the time. More than half of the periods recorded returns below 10%, while roughly 13% of the periods were negative. The weakest 12-month period produced a loss of about 5.2%, whereas the strongest generated a gain of 45.5%.

In other words, a five-year annualised return of 12.92% does not mean an investor will earn 12.92% in every year. “The easy answer to ‘what could it earn’ is a rate. The more uncomfortable answer is a date,” Soni said.

That distinction is important when comparing a guaranteed purchase price with a market-linked investment. The Rs 4.49 lakh required for the iPhone Duo is known upfront. What an investment of the same amount will be worth after a year is not.

SIP Or Lump Sum: Why The Difference Matters

The comparison also changes if the entire Rs 4.49 lakh is available for investment on the first day. At an assumed annual return of 12%, a lump-sum investment of Rs 4.49 lakh could grow to around Rs 5,02,880 after one year, representing a gain of approximately Rs 53,880.

That is considerably higher than the roughly Rs 4.78 lakh projected value of the SIP because the full lump sum gets the opportunity to remain invested for the entire year. In an SIP, the money enters the market gradually. The first instalment remains invested for 12 months, while the final instalment is invested for only one month.

However, an SIP remains the more relevant comparison when weighing an investment against buying the phone through monthly payments. Both involve the same basic cash-flow pattern: money leaves the buyer’s account each month in the case of an EMI, while the same amount could instead be invested through an SIP.

“The case for a SIP was never a steady market. It’s an unsteady one,” Soni said. That is also why judging the investment purely on its one-year performance can miss the larger picture.

Longer Investment Horizons Change The Picture

The potential difference becomes more pronounced when the money remains invested for several years. Consider a scenario in which Rs 37,417 is invested every month for 12 months, after which no additional contributions are made and the accumulated corpus is left invested.

At an assumed annual return of 10%, the investment could grow to around Rs 5.72 lakh after three years, Rs 6.92 lakh after five years and Rs 11.15 lakh after 10 years. At 12%, the corresponding figures would be approximately Rs 5.99 lakh, Rs 7.52 lakh and Rs 13.25 lakh.

At an assumed 15% annual return, the corpus could reach around Rs 6.41 lakh after three years, Rs 8.48 lakh after five years and Rs 17.05 lakh after 10 years. These figures are mathematical projections rather than guaranteed outcomes.

The longer-term calculations highlight why equity investments are generally better evaluated over extended periods instead of using a single year’s performance as the benchmark. Market returns can fluctuate considerably in the short term, while the effect of compounding becomes more significant over longer periods.

Should You Buy The iPhone Duo Or Invest The Money?

For someone who has already decided that the iPhone Duo is worth buying, an investment comparison may not change the decision. A financial investment cannot provide the utility, convenience or enjoyment expected from a new smartphone.

“If the phone genuinely makes your work or your life better, that’s a fair trade,” Soni said.

For buyers who are undecided, however, the comparison provides a useful way to think about the cost. A Rs 4.49 lakh smartphone is likely to depreciate over time, although how quickly Apple’s first-generation foldable will lose value remains uncertain. An equity investment carries market risk, but unlike a depreciating device, it has the potential to increase in value over several years.

The financing method also matters. A monthly EMI can make a Rs 4.49 lakh purchase appear more manageable, but buyers should consider the total amount they will eventually pay, including interest and applicable taxes, rather than looking only at the monthly instalment.

Ultimately, the choice is not simply between a phone and a mutual fund. It is between spending Rs 4.49 lakh on a piece of technology today and giving that money an opportunity to grow over time. The iPhone’s price tag tells you what the device costs, but not the potential value of what you give up by choosing to spend the money now.

As Soni puts it, “The number that matters isn’t the return. It’s the number of years.”

The iPhone Duo may fold in your hand, but the more consequential question for a buyer could be what Rs 4.49 lakh might unfold into over the next decade.

Long or Short, get news the way you like. No ads. No redirections. Download Newspin and Stay Alert, The CSR Journal Mobile app, for fast, crisp, clean updates!

App Store –  https://apps.apple.com/in/app/newspin/id6746449540 

Google Play Store – https://play.google.com/store/apps/details?id=com.inventifweb.newspin&pcampaignid=web_share

Latest News

Popular Videos